How Can I Calm Money Worries and Build Financial Confidence?
Money worries can feel more manageable when you combine emotional support with one practical step at a time. Start by identifying the most urgent issue, seek help early if a payment is at risk, and give yourself permission to approach the situation without judging yourself. Financial confidence does not mean having every answer. It can begin with opening one letter, asking one question or making one call.
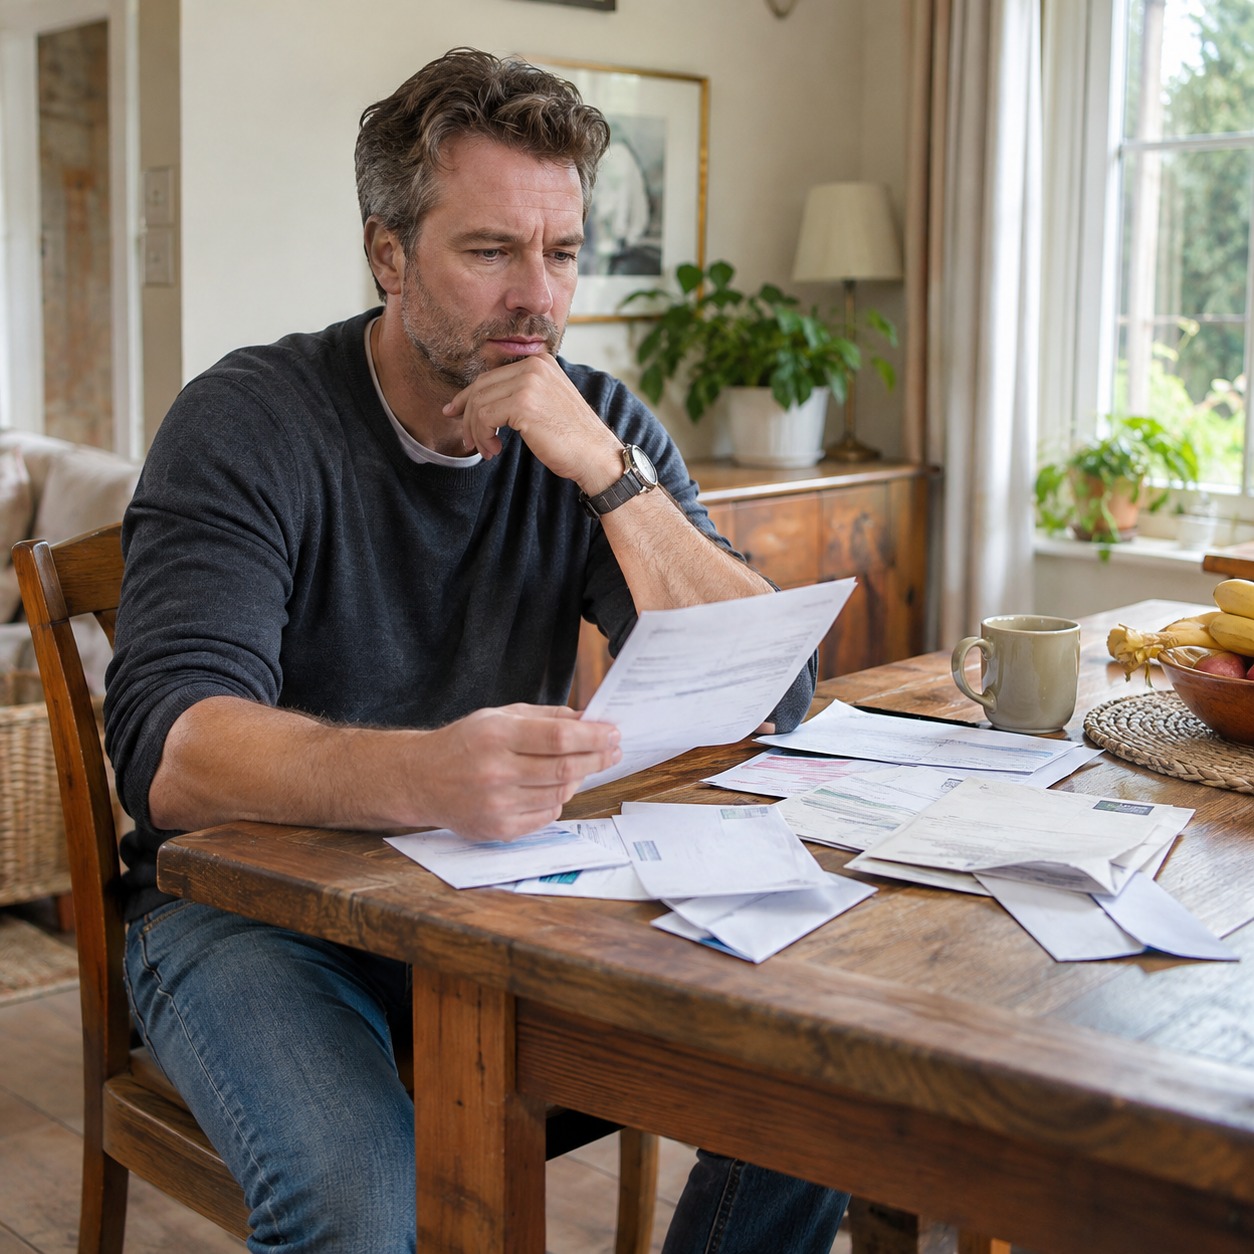
A table covered in bills can feel like a verdict on your life. It is not. Those papers describe commitments and circumstances; they do not describe your worth. This guide brings together practical UK and US support and a gentle way to work with the feelings that can make money tasks harder.
What does financial confidence actually mean?
Financial confidence means feeling able to engage with your finances, recognise when you need advice and take decisions based on your circumstances. It does not require a high income, a perfect budget or certainty about the future.
For someone with irregular work, confidence might mean checking what is due before the next payday. For a couple, it might mean discussing a bill without blame. For someone avoiding their bank balance, it might mean looking at the figures with a trusted person beside them.
Low income, rising costs and unexpected expenses are real pressures. They are not personal failures, and a change of mindset alone cannot remove them.
What can I do when money worries feel overwhelming?
1. Pause long enough to notice what is happening
Before opening the banking app or sorting the post, place your feet on the floor and let your breathing settle at a comfortable pace. Notice the feeling you are carrying: fear, shame, frustration or exhaustion. You do not need to force it away.
The NHS guidance on money worries and mental health recommends self-kindness, talking to someone you trust and making space for relaxation. A short pause can be a way to prepare for the task in front of you.
2. Separate the facts from the judgement
“This bill is due on Friday” is a fact. “I always ruin everything” is a judgement. Write down the amount, the due date and anything you need to find out. Keeping the information specific gives you something concrete to work with.
You might say to yourself: “I feel worried about this, and I can still ask for help.” You do not have to feel completely calm before taking a useful step.
3. Choose one manageable action
Try a short, planned money appointment during the day. Gather the relevant paperwork and choose one task: list upcoming payments, contact a provider or arrange a debt-advice appointment. If a letter contains a deadline, act on it promptly rather than waiting for your next planned session.
If you cannot cover everything, get advice about the consequences of missed payments. The loudest demand is not necessarily the most urgent. Do not agree to a repayment arrangement you do not understand or cannot afford.
4. Make room for support
You could ask someone you trust to sit with you while you make a call. A simple opening is: “I have been avoiding this because I feel overwhelmed. Could you help me look at the next step?” You can share only what feels appropriate.
If worry is persistently affecting sleep, mood or daily life, speak to a healthcare professional as well as seeking financial help. The NHS guide to coping with financial worries includes information about when to seek medical support.
Where can I get help with money worries in the UK?
Free, confidential debt advice is available. You do not need to wait until your situation becomes an emergency. MoneyHelper’s debt advice locator helps you find support online, by phone or locally. An adviser can explain options and help identify benefits or entitlements you may be missing.
The Financial Conduct Authority’s guidance on rising living costs recommends listing what you owe, identifying priority commitments and contacting your lender or provider early if payments are becoming difficult. Housing, council tax or rates, and energy arrears can have particularly serious consequences. The right approach depends on your situation and where you live.
If you are already behind, or facing eviction, enforcement or disconnection, seek advice urgently. Use GOV.UK’s free debt-advice directory to find organisations and routes for the different UK nations, including StepChange and Citizens Advice.
Where can I get help with financial stress in the US?
The Consumer Financial Protection Bureau’s “Behind on bills” resources offer tools for organising income, expenses and an action plan. Its prioritising bills worksheet focuses on the consequences of missed payments, including protecting housing and income.
If a credit-card payment is becoming unaffordable, the CFPB recommends contacting the card company promptly. Explain the difficulty and ask what support is available. Avoid services promising to make debt disappear.
A reputable credit counselor can help you review your circumstances and budget. Many organisations are nonprofits, but some services have fees. Ask for costs in writing and understand any proposed agreement. The CFPB’s credit-counseling guide explains how to assess an organisation and find support.
For help with essentials, USAGov’s financial-hardship hub links to food, housing, utility and other assistance programmes. Eligibility and availability vary. Its emergency rent assistance page explains how to find state and local help, including through 211.
How does the Letting Go approach fit alongside practical help?
In this recording, letting go means making space for the feelings that arise around money, without treating those feelings as instructions or as a definition of who you are. It might begin with noticing the tightness that appears before you check a balance, rather than immediately closing the app.
You can gently ask: “Could I allow this feeling to be here for a moment?” Then choose the next useful action. The aim is not to suppress concern or ignore a bill. It is to practise meeting the situation with less self-criticism.
Build Financial Confidence is a guided hypnosis recording narrated by Theo, with Mystic Dawn (Theta) by Christopher Lloyd Clarke. Its approximately 31-minute session includes relaxation, guided reflection on everyday money situations and a gradual return to ordinary alertness.
The recording is offered for relaxation and general wellbeing. It does not provide financial advice, treat a mental-health condition or promise debt reduction, greater earnings or a particular result. The official sources in this article support the practical guidance; they do not endorse this recording.
Frequently asked questions
Can hypnosis solve money problems?
No recording can pay bills, increase income or replace debt advice. Guided hypnosis offers an optional space for relaxation and reflection alongside practical support. Individual experiences vary.
What should I do first if I cannot pay a bill?
Check the deadline and seek help promptly. Contact the provider to explain the situation and use the UK or US support links above. If housing or essential services are at risk, make that clear when asking for advice.
Do I need to buy the recording?
No. You can listen to the full recording free on YouTube below. The paid MP3 is an optional way to own an ad-free copy permanently, with no subscription.
When should I listen?
Choose a quiet, safe place where you can rest without interruption. Do not listen while driving, operating machinery or doing anything that requires attention. Stop if you feel uncomfortable. The session ends with a gradual return, so allow time to become fully alert before continuing your day.
Watch Build Financial Confidence free on YouTube
Listen to the full session on the Letting Go Hypnosis channel: Hypnosis for Money Worries | Build Financial Confidence (31 Minutes).
Watch the full recording on YouTube · Visit the Letting Go Hypnosis channel
Own the ad-free recording
Download Build Financial Confidence — keep your MP3 forever, with no subscription.
Browse all hypnosis recordings · Get the Letting Go Hypnosis Android app · Visit lettinggohypnosis.com
Sources checked: 11 November 2026. This article provides general information and wellbeing support, not personalised financial, legal or medical advice. Support options depend on your circumstances and location.